
Instant payments elevate the customer experience by replacing traditional payment methods, like paper checks and manual ACH, with nearly immediate transactions. Demand for faster ways to move money is growing, in fact, 92% of businesses now use some form of faster payments, including instant payments, Same Day ACH and digital wallets.
In this blog, we'll explore the fundamentals of instant payments and how they digitally transform consumer and business payments.
What are Real-Time Payments?
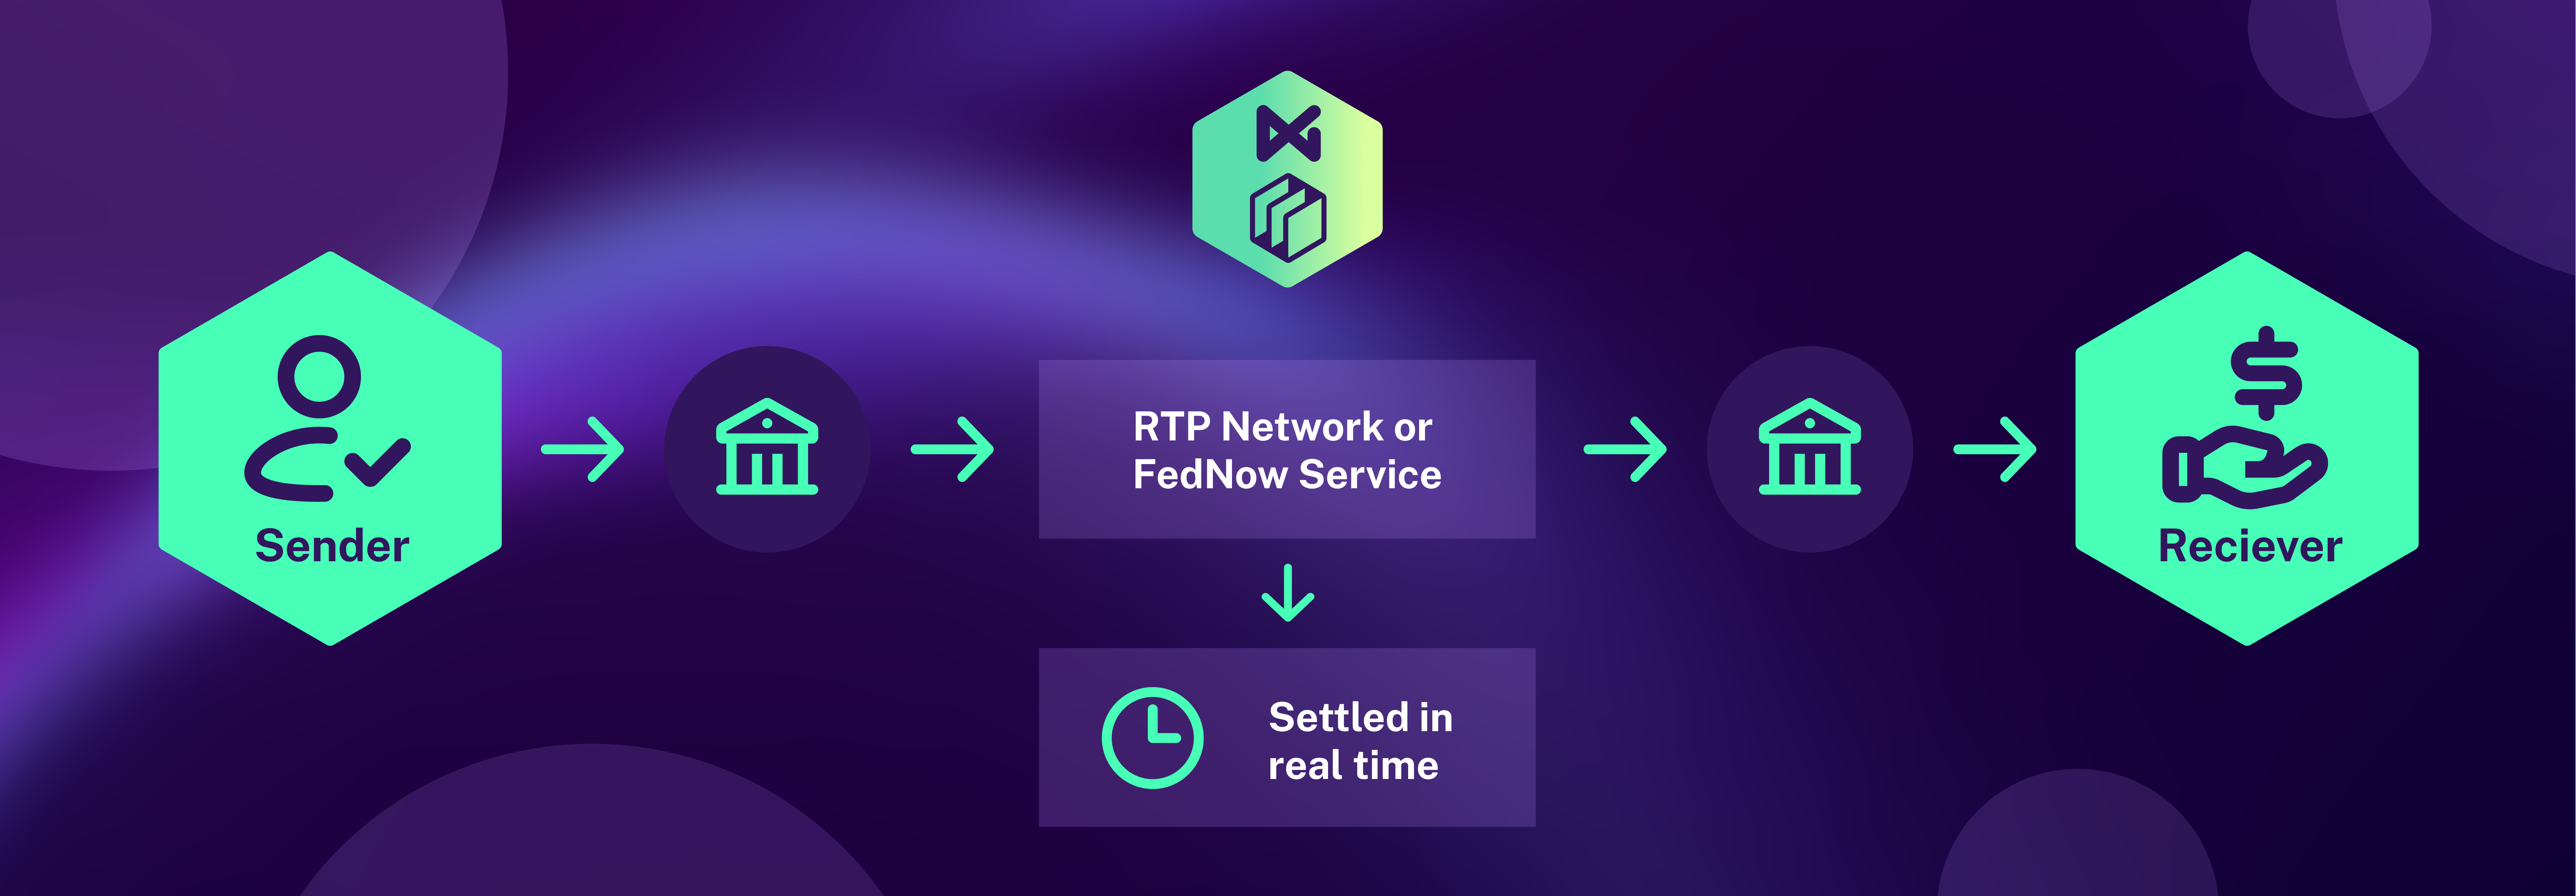
Real-Time Payments (RTP) are account-to-account transactions (also known as pay-by-bank transactions) that clear and settle near instantaneously. Transactions sent via the RTP® network and the FedNow® Service are credit-only transfers, meaning they can be used to send funds but not debit or pull funds from someone else’s account. The instant payment systems support extensive remittance data that can be used to reconcile funds efficiently, and since the transactions settle within seconds, all transfers are final.
RTP transfers are sent via The Clearing House’s® RTP network, which was launched in November 2017. Averaging more than 1 million payments per day, the RTP network’s capabilities have grown in recent years, making it accessible to more banks and financial institutions (FIs) across the country. In 2025, the RTP network experienced a 490% increase in total transaction value ($1.21 trillion) compared to the previous year.
What is FedNow?
The FedNow Service is an instant payment system created by the Federal Reserve that enables banks and credit unions to offer their customers the ability to send and receive payments in near real-time, 24 hours a day, seven days a week, 365 days a year.
The Federal Reserve launched FedNow in July 2023. This service processed 8.4 million transactions in 2025 and during Q2 2026, volume increased by more than 80% compared to Q1, with billions of dollars moving through the service per day. A list of participating financial institutions is continuously updated and can be found on the FedNow Service website. As of the date of publication, there are 1800+ financial institutions live on the FedNow system.
What is a Request for Payment (RFP)?
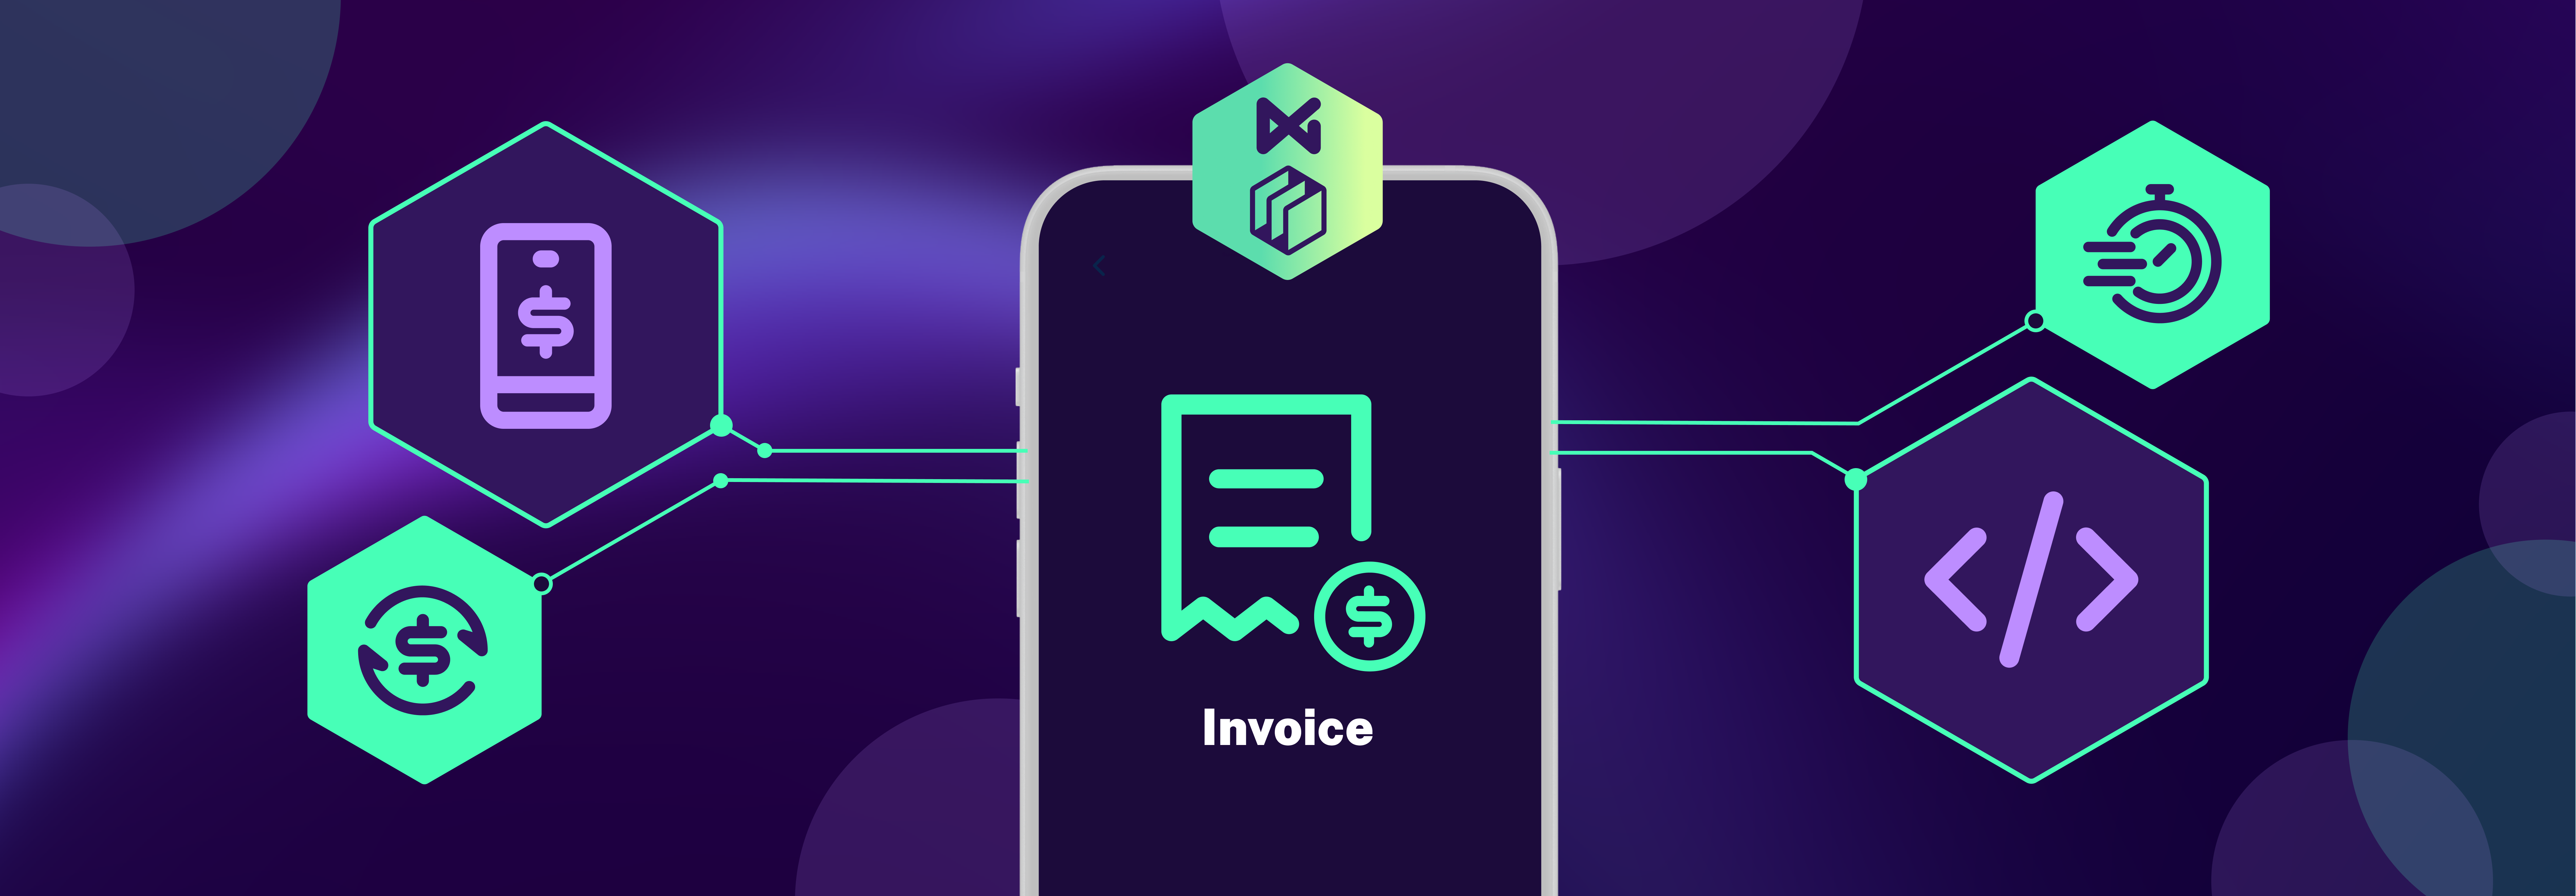
Request for Payment (RFP) is an emerging feature within the world of instant payments that introduces a unique twist. Unlike traditional instant payments where the sender initiates the transfer, RFP empowers the recipient to initiate the transfer.
With Request for Payment (RFP), your organization can trigger an electronic invoice that lands directly inside a payer’s mobile-banking app—no portals or paper required. The recipient reviews the details and, with one tap, authorizes the transfer. Behind the scenes the funds move from the payer’s bank to your account over RTP or FedNow, settling almost instantly. That means you get paid in real time, eliminate manual bill entry, and gain end-to-end data visibility between both financial institutions, all while giving employees or vendors a consumer-grade payment experience.
“Pull" transactions hold immense potential. Businesses can benefit from faster payments and improved cash flow. Simplified bill payments and early payment discounts make consumer experiences more convenient and rewarding. Additionally, RFP opens doors for innovative payment models like subscription services with automatic recurring payments and instant micro-transactions.
However, widespread adoption requires overcoming obstacles. Limited functionality by financial institutions and the lack of industry-wide standardization pose challenges. The development of robust frameworks is necessary to mitigate potential fraud risks in "pull" transactions. It remains to be seen how quickly the industry will be able to overcome those obstacles and allow businesses and consumers to take advantage of RFP use cases.
Instant Payments Adoption in the United States
Instant payments in the United States are experiencing a surge in adoption. A U.S. Bank study revealed that over 40% of companies exceeding $100 million in revenue already leverage The Clearing House's RTP network for instant transactions. This positive trend is further bolstered by forecasts indicating that nearly 70% of businesses anticipate adopting instant payments through the RTP network or the FedNow Service within the next year.
Consumer preference plays a significant role in driving this shift. Research by PYMNTS Intelligence demonstrates a staggering 90% of consumers would opt for instant disbursements when offered.
A key piece of instant payments adoption, however, is FI adoption of the two instant payment rails. The RTP network currently has 1300+ FIs participating, and the FedNow Service has 1,800+ FIs participating. For instant payments to reach true ubiquity in the United States, The Clearing House and the Federal Reserve will need to continue encouraging adoption among financial institutions and work toward greater interoperability between their two systems, something that doesn’t exist today.
Businesses are recognizing the potential of instant payments to enhance customer satisfaction and improve cash flow through faster transactions. While challenges still persist, the combined force of consumer preference and the inherent benefits of instant payments is creating a compelling scenario for continued growth in adoption within the U.S. enterprise landscape.
How Can Enterprises Use Instant Payments to Gain a Competitive Edge
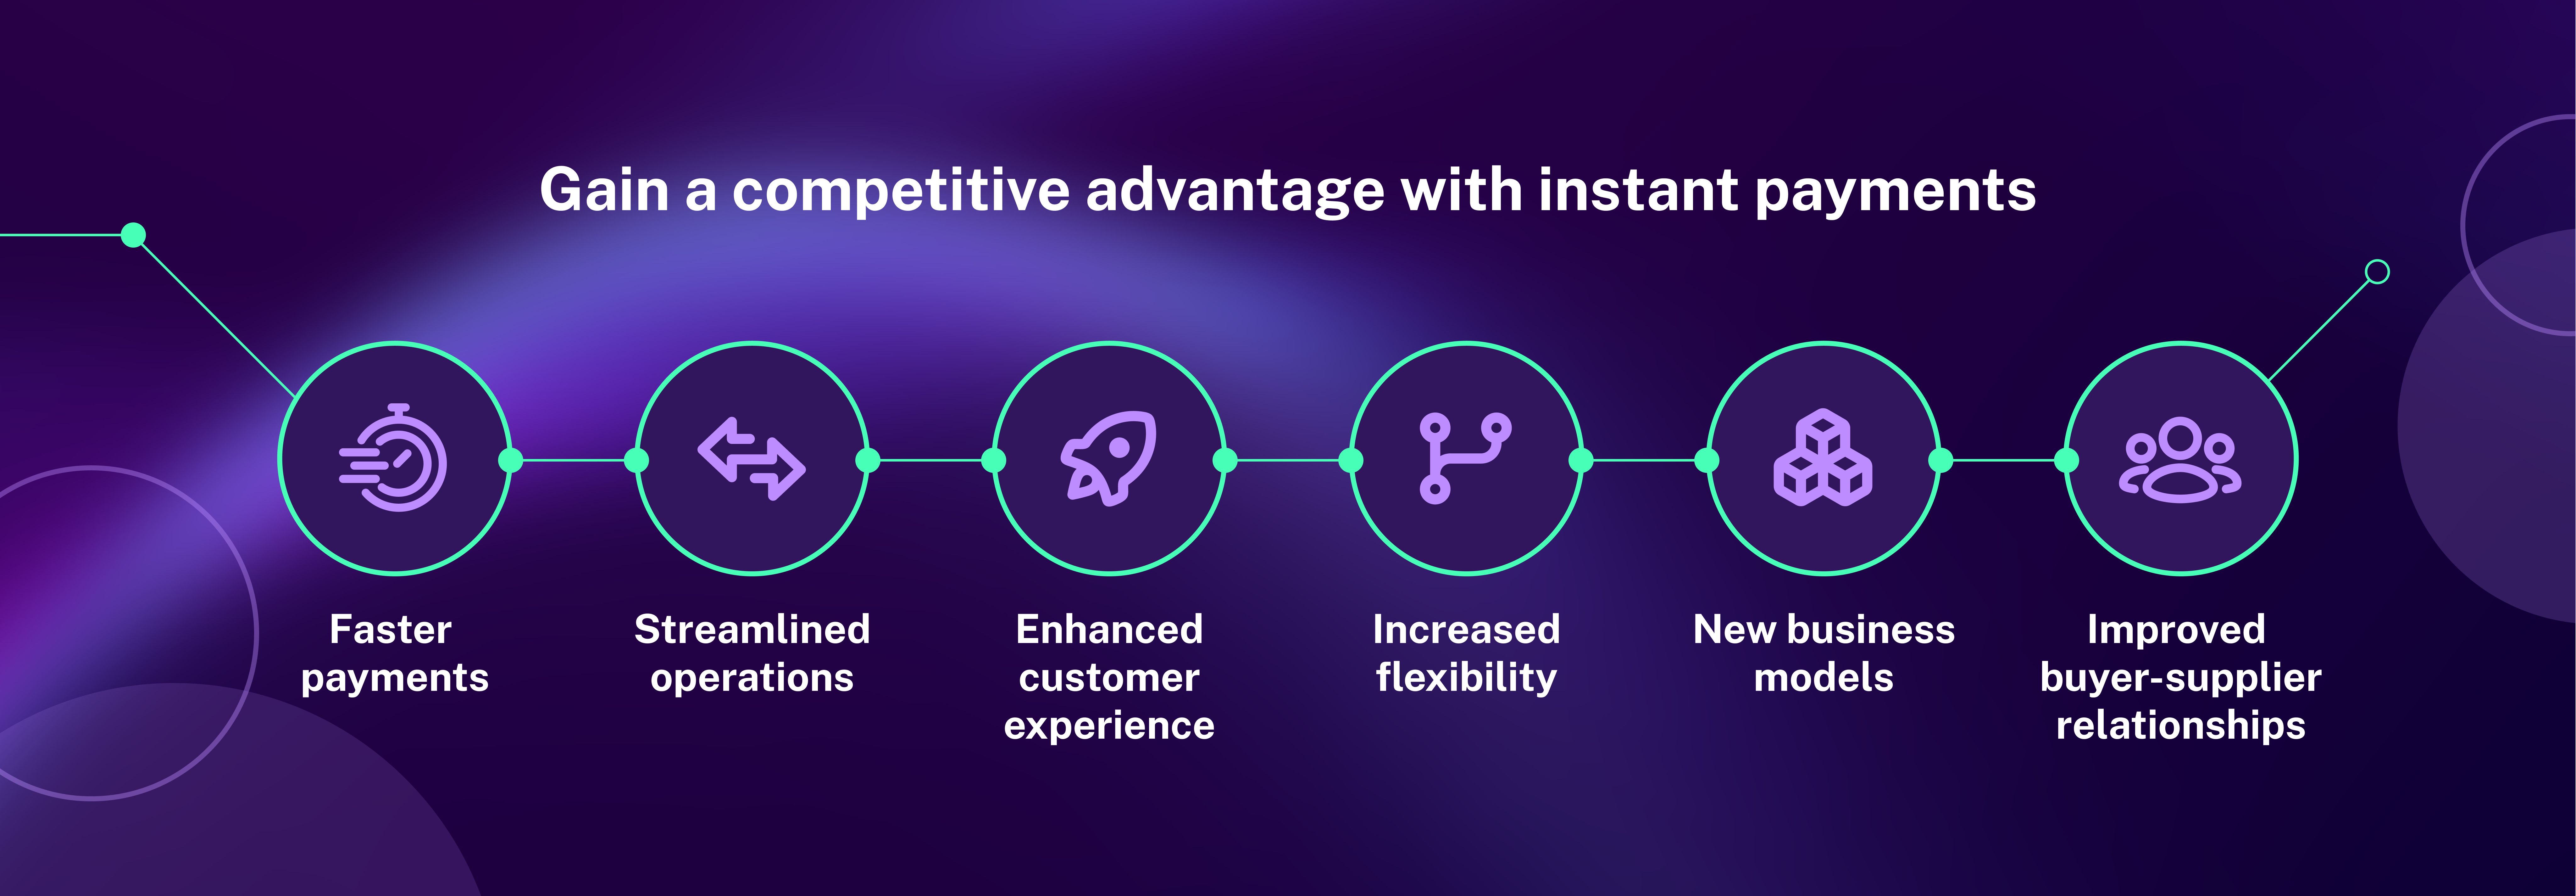
Instant payments offer enterprises tangible operational advantages that extend far beyond speed alone. By enabling immediate fund transfers and settlements, businesses can transform their payment processes, enhance customer relationships and create new opportunities for growth. Here's how instant payment services improve business operations:
- Faster Payments: Businesses can utilize instant payments to send and receive payments, allowing quicker access to funds, improved cash flow management and faster fulfillment of orders. This can be particularly beneficial for a broad range of electronic payment use cases across industries, such as:
→ Claim payouts: Traditional claim processing can take days or weeks, leaving policyholders waiting for crucial funds for repairs or replacements. Instant payments allow insurers to disburse funds immediately, providing faster financial relief and improved customer satisfaction.
→ Gig economy payments: Independent contractors, freelancers or other gig workers can be compensated instantly upon completing tasks, improving their financial well-being and creating better payment visibility.
→ Merchant settlements: Businesses can immediately receive payments for goods and services rendered from customers, shortening settlement time, eliminating delays and facilitating faster access to revenue.
→ Real estate payments: Frequently working against the clock or in competitive markets, mortgage and real estate lending companies can benefit from faster transactions and payment services.
- Streamlined Operations: The extensive remittance data accompanying each instant payment transaction helps businesses automate reconciliation processes and gain valuable insights into payment flows. This saves time and resources, allowing for better financial management and decision-making.
- Enhanced Customer Experience: Businesses offering instant payment options can provide customers with a faster, more convenient checkout experience, increasing customer satisfaction and loyalty.
- Increased Flexibility: The RTP network and the FedNow Service operate 24/7/365, enabling businesses to conduct transactions outside traditional business hours and cater to customers in different time zones or with flexible schedules.
- New Business Models: The speed and security of instant payments can facilitate the development of innovative business models, unlocking new revenue streams and opportunities.
- Improved Buyer-Supplier Relationships: Instant payments can help build trust with suppliers, improve their cash flow and unlock discounts for buyers. In manufacturing, this can help businesses foster stronger partnerships and promote a smoother-running supply chain.
Dwolla by NMI’s single API gives enterprises access to the RTP network and the FedNow Service, enabling faster, more secure and streamlined pay-by-bank payments any day of the year.
To keep up with the evolving payments landscape, see what's new on the NMI Blog here.
Ready to get started? Schedule a consultation with a payments expert.